
 11
 0
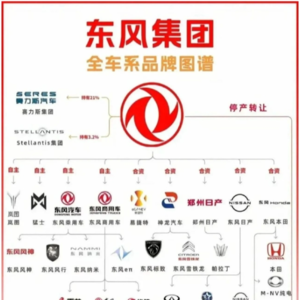
Erinome:Hello dear friends, today we are going to talk about a big news in China’s car industry—Dongfeng Motor, a famous state-owned car company, is delisting from Hong Kong stock market and going private. Enceladus, have you heard about this?
Enceladus:Wow, really? Dongfeng is one of the "big three" state-owned car groups, right? I thought listed companies usually want to stay on the market. Why would they leave on purpose?
Erinome:That’s exactly what everyone is asking! You know, in China’s capital market history, central state-owned enterprises (SOEs) almost never do "voluntary delisting"—most delist because they’re in trouble. But Dongfeng is different. It’s like a bold new move!
Enceladus:So… delisting can be "voluntary"? I thought companies only delist when they’re failing.
Erinome:Oh no, there are two types! One is "involuntary delisting"—when business is bad, can’t meet listing rules. The other is "voluntary"—the company is okay, but the market values it too low, so listing isn’t useful for raising money. Dongfeng is definitely the second one!
Enceladus:Low valuation? How bad is it?
Erinome:Let me show you the numbers. In July, Dongfeng’s Hong Kong stock price was only 3.4 Hong Kong dollars per share. Its PB ratio—you know, price-to-book ratio, which is market value divided by net assets—was 0.16. Even before the stock stopped trading on August 8th, the price doubled to 6 Hong Kong dollars, but PB was still only 0.3!
Enceladus:0.3? What’s normal?
Erinome:Normally, a healthy company’s PB is more than 1. If it’s below 1, the market thinks its assets can’t make money in the future. Like, if Dongfeng has 10 billion net assets, the market only says it’s worth 3 billion. That’s super low!
Enceladus:Is this only Dongfeng?
Erinome:No, most global fuel car companies are in this "valuation winter". Their PB ratios are often 0.1-0.2. But new energy car companies? Oh, their average PB is over 5! Big difference, right?
Enceladus:So Dongfeng got stuck in the fuel car low valuation, and wants to get out?
Erinome:Exactly! Other fuel car companies like Nissan or Mercedes just say "we’re okay" but do nothing. But Dongfeng said, "We have money, we believe in ourselves—let’s buy back the cheap shares!"
Enceladus:How do they pay shareholders?
Erinome:Smart plan! They offer 10.85 Hong Kong dollars per share. That’s 80% higher than the 6 Hong Kong dollars before trading stopped. And it’s "cash + stock": 6.68 Hong Kong dollars cash (more than the market price) plus 1 share of LanTu Auto, which is worth 4.17 Hong Kong dollars.
Enceladus:LanTu Auto? What’s that?
Erinome:LanTu is Dongfeng’s new energy brand—like their "secret weapon"! Dongfeng owns 79.67% of LanTu. And after this, LanTu will list in Hong Kong through "introduction listing".
Enceladus:Introduction listing? What’s that? Is it like IPO?
Erinome:No, different! IPO means issuing new shares to raise money. Introduction listing is just listing existing shares—no new shares, no fundraising. It’s like "let the shares start trading publicly" without selling new ones.
Enceladus:Why do that for LanTu?
Erinome:Because LanTu is growing fast! In July, it delivered 12,135 cars—up 102% from last year, and 21% more than June. Six months of sales growth in a row!
Enceladus:But is LanTu making money?
Erinome:Um, not yet, but getting better! From 2022 to 2024, it lost 1.538 billion yuan, then 1.496 billion, then only 90 million yuan. Less loss each year—good sign!
Enceladus:So shareholders get cash now and LanTu stock for future? That’s a good deal!
Erinome:Yes! Small shareholders are happy—cash in hand, plus a "growth stock". No wonder the market liked it: Dongfeng’s US ADR (like a stock for US investors) jumped 87.69% on August 22nd!
Enceladus:Wow, that’s a big jump. What does this mean for other state-owned companies?
Erinome:Huge! Before, no central SOE did voluntary privatization. Dongfeng showed they can use capital smartly—switch from "old fuel car valuation" to "new energy valuation". It’s a model for other SOEs to转型 (zhuanxing, "transform").
Enceladus:Oh right! Dongfeng’s合资 brands (hezi pinpai, "joint venture brands") like Dongfeng Nissan and Honda are doing badly—sales down 23.5% and 37.4% this year. So they need to focus on their own new energy brand!
Erinome:Exactly! Instead of "fighting" in the low-valuation fuel car market, they’re "moving the chess piece" to LanTu. Like "腾笼换鸟" (teng long huan niao, "replace the old cage with a new bird")—out with the old fuel car listing, in with the new energy LanTu!
Enceladus:So Dongfeng isn’t leaving the market, just rebranding their value?
Erinome:Yes! The delisting is to let LanTu shine. Investors can now see LanTu clearly, not mixed with Dongfeng’s old fuel car assets.
Enceladus:What did people think about this plan?
Erinome:The US ADR price jumping 87.69% says it all! International investors love the idea—they believe LanTu can get the new energy valuation.
Enceladus:Is this important for China’s car industry?
